

DailyPay On-Demand Pay

- 18.86K Reviews
- 4.7
- Downloads
- 1,000,000+
Our take on DailyPay On-Demand Pay from Appgk
I look at DailyPay On-Demand Pay as a practical finance app for a very specific problem: the uncomfortable stretch between finishing work and reaching the next regular payday. Developed by DailyPay Inc, it gives eligible workers a way to access wages they have already earned through the mobile app instead of waiting for the usual payroll schedule. That sounds simple, but the value becomes clearer when a bill, grocery trip, or transport cost arrives at the wrong point in the pay cycle.
My overall impression is that it is most useful as a short-term cash-flow tool, not as a replacement for budgeting or a permanent solution to insufficient income. The app is free to download, has an Everyone age rating, and belongs in the finance category. Its public reception is notably strong, with a 4.7 average from around 238 thousand ratings and more than a million installs. Those figures suggest that the basic idea is easy for many people to understand, although personal eligibility and the exact experience can depend on the employer and payroll arrangement connected to the account.
How DailyPay fits into real life today
A bridge between work and payday
The central experience is different from taking out a conventional loan. Instead of applying for money based on future income, I would use the app to reach part of pay already earned from completed work. That distinction matters psychologically and financially. It can help someone handle an urgent expense without committing to a longer repayment schedule, provided the withdrawal is genuinely tied to earned wages and the user understands the conditions shown in the app.
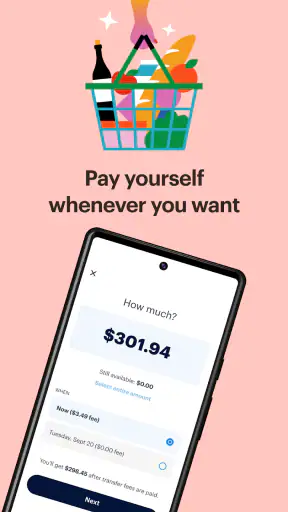
A realistic example would be a worker who has completed several shifts but still has days to go before payday. Their phone bill is due, the car needs fuel, and waiting could create a late payment or make it harder to get to work. DailyPay can be useful in that narrow window: open the app, check what is available, choose the amount needed, and use the funds for the immediate expense. I would deliberately take only what solves the problem rather than treating the available balance as extra spending money.
Best Parts of DailyPay On-Demand Pay
Things to Keep in Mind About DailyPay On-Demand Pay
That habit is important because early access changes the timing of income, not the total amount earned. After using part of a paycheck ahead of schedule, the regular payday deposit may be smaller than expected. Someone who forgets that can solve today’s problem and create another one later. For me, the app works best when it is paired with a simple note in a budget: record the amount accessed, the reason for it, and what the next paycheck needs to cover.
Who is likely to benefit most
DailyPay makes the most sense for people whose employers support the service and whose income arrives on a predictable payroll cycle. It can be especially helpful for workers dealing with variable weekly expenses, long gaps between paydays, or occasional costs that cannot wait. A modest timing problem can be much easier to manage when the money has already been earned.
News and Features Related to DailyPay On-Demand Pay

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
It may also help someone avoid using a credit card for a small, necessary purchase when they know repayment would otherwise be immediate. That does not automatically make early wage access free in every situation, so I would read the withdrawal details before confirming anything. The right comparison is not only “can I get this money now?” but also “what will this choice leave available for my normal payday?”
I would be more cautious if the user regularly needs an advance every pay cycle. Repeated withdrawals can become a symptom of a budget that does not match income timing. In that case, a spending plan, emergency fund, payroll conversation, or professional financial guidance may be more useful than relying on the app indefinitely.
Don't want to read the full review?
The first-use experience and the details worth checking
When setting up a finance app that touches payroll, I would slow down rather than rushing through the opening screens. The important questions are whether the employer is supported, how the app identifies the user’s employment and earned balance, when a transfer should arrive, and whether the chosen delivery method has a charge or other condition. The app’s purpose is straightforward, but the practical result depends on those account-specific details.
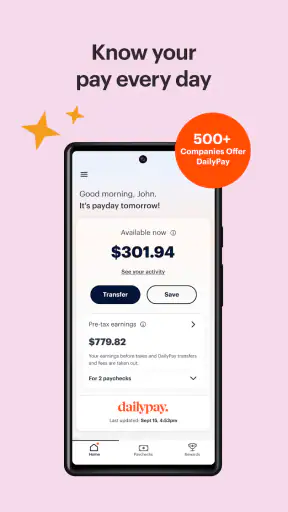
I would also check the available amount against actual completed work rather than assuming it equals the next paycheck. Earned access and final take-home pay are not necessarily the same thing. Taxes, deductions, benefits, and payroll adjustments can affect what ultimately arrives on payday. Treating the displayed balance as a guaranteed duplicate of the final deposit would be a mistake.
Screenshots
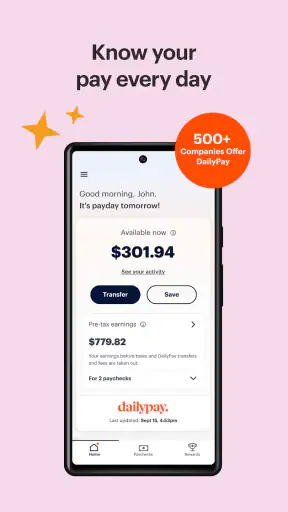
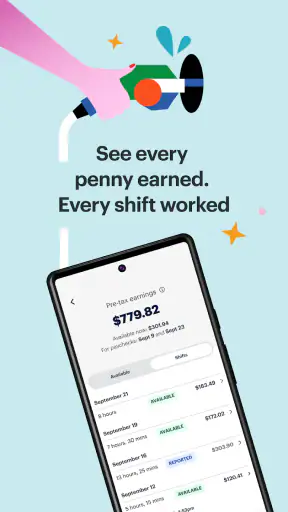
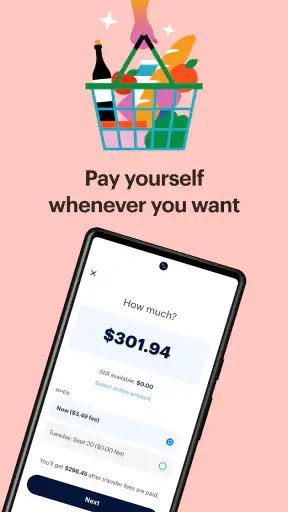
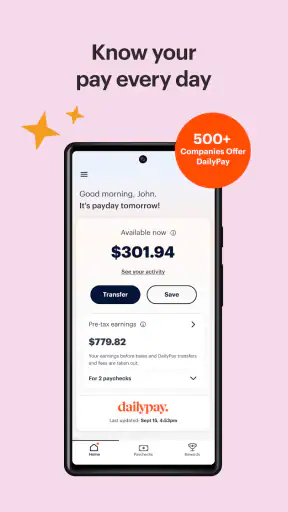
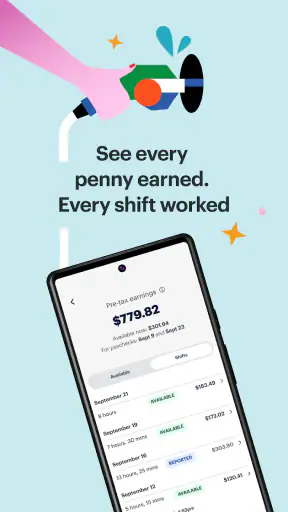
One useful workflow is to use the app only after naming the expense. “Rent shortfall,” “prescription,” or “fuel for work” is a better reason than simply seeing a balance and withdrawing because it is there. That small pause turns DailyPay from an impulse-spending channel into a controlled cash-flow decision.
What the current version suggests about product maturity
The current version is 52.0.0, which indicates an actively maintained product rather than a one-off utility frozen after launch. DailyPay first appeared on December 7, 2018, so the app has had time to develop around a real recurring need. I see that history as a sign that the service is intended to sit inside an ongoing payroll routine, not merely provide a novelty transfer once.
At the same time, a version number alone does not tell me that every part of the experience is perfect. Finance apps can feel polished while still leaving users with questions about timing, eligibility, transfer methods, or the effect on their next paycheck. I would judge updates by whether they make those decisions clearer, reduce unnecessary friction, and help users understand the consequences before they confirm a withdrawal.
How it compares with ordinary alternatives
The usual alternatives each solve a different part of the problem. A traditional bank account and emergency fund are generally better for planned resilience because they do not require moving future cash flow forward each time an expense appears. A credit card can offer flexibility, but it may carry interest if the balance is not cleared. A personal loan is designed for larger borrowing and a longer repayment structure, which can be excessive for a small timing gap.
DailyPay occupies a middle ground: it is closer to payroll access than to borrowing in the conventional sense. That can make it more suitable for a short-lived mismatch between earned income and the calendar. It is less suitable when the expense is large, recurring, or unrelated to wages already earned. In those cases, a savings plan or a carefully evaluated financial product may offer a more stable answer.
I also would not compare it directly with a standard budgeting app. Budgeting tools help decide where money should go; DailyPay helps change when some earned money becomes available. The two can work together, but neither replaces the other. If the main problem is not timing but spending more than income, early access alone cannot fix it.
Where the experience can become frustrating
The biggest limitation is that access is not entirely under the user’s control. The employer and payroll connection matter, so downloading the app does not by itself guarantee that every worker can use the service in the same way. Someone deciding whether to install it should first think about their employment setup and then verify the account details during registration.
Timing is another point where expectations need to stay realistic. “Available before payday” does not mean every transfer will behave like instant cash in every circumstance. Delivery choices, processing steps, weekends, payroll updates, or account issues can affect the practical arrival time. If an expense has a hard deadline, I would not wait until the final possible hour to request funds.
There is also a mental accounting risk. Seeing earned wages in an app can make them feel separate from the paycheck, even though they are part of the same income. That separation may encourage spending twice: once through an early withdrawal and again when the remaining paycheck arrives. The safest approach is to regard the app’s balance as an early view of money already assigned to upcoming obligations, not as a bonus.
What existing users should notice after updates
For someone already using the service, the move to version 52.0.0 is a reason to review the app rather than assume the routine is unchanged. I would look for clearer explanations around available earnings, transfer selection, confirmation screens, and account activity. Even a small wording change in a finance app can affect how confidently a user understands the amount being moved.
I would also revisit notification and transaction habits after an update. Keeping a personal record of withdrawals makes it easier to reconcile the next paycheck and spot anything unexpected. If the interface presents more than one route for receiving funds, I would compare the timing and any displayed cost each time instead of automatically selecting the first option.
Existing users should pay attention to the difference between an app update and a change in their employer’s payroll arrangement. A new app version can improve the interface, but it cannot make an employer-supported connection behave differently unless the underlying payroll setup also supports that change. When something looks different, checking the transaction details is more useful than relying on memory from an earlier version.
Three practical habits that improve the experience
Withdraw for a named need, not for the maximum shown. This keeps early access tied to a real expense and protects more of the next payday.
Check the final confirmation carefully. Look at the amount, destination, expected timing, and any displayed charge before approving the transfer. A few seconds of review can prevent an avoidable cash-flow surprise.
Reconcile after payday. Compare the early access activity with the remaining deposit and your budget. This is especially useful if your hours, deductions, or work schedule change from one pay period to another.
These habits are more valuable than simply knowing that the app offers earned wage access. They address the trade-off at the heart of the product: convenience now can reduce flexibility later. The app gives users a faster decision, but it does not remove the need to make a careful one.
Questions I would answer before relying on it
Would I use it for an emergency? Possibly, if the amount were modest, the wage balance were clearly available, and I had checked the delivery details. Would I use it for a routine subscription every month? No. A recurring subscription should fit the normal budget, because repeatedly advancing wages can hide a structural shortfall.
Would I recommend it to someone with irregular work hours? I would recommend extra caution. Variable earnings make it harder to predict what the next paycheck will contain, so the user should avoid assuming that today’s available amount represents a stable future pattern. The app may still help, but the withdrawal should be smaller and connected to a clearly necessary expense.
Is it useful if the user already has a healthy emergency fund? It can still be convenient, but the fund may be the better first choice if using DailyPay introduces a charge or makes the next paycheck harder to manage. Early wage access is not automatically superior simply because it is quick.
What if the user cannot connect their employment or does not see the expected balance? I would treat that as a setup or eligibility issue to resolve before planning around the money. I would not make a time-sensitive payment based on an amount that has not actually appeared as available in the account.
Can it replace a bank account? I would not view it that way. Its role is focused on accessing earned pay, while a bank account handles broader everyday money management. The app is most effective as one part of a financial routine, not as the entire routine.
What I would like to see continue improving
The most important area to watch is transparency at the moment of choice. Users should be able to understand exactly how much they are accessing, what remains for payday, how quickly the funds should arrive, and whether the selected route has a cost. Those details matter more than decorative changes because they directly affect financial decisions.
I would also watch how the product handles unusual situations: corrected time records, changed shifts, employment transitions, payroll delays, and a transfer that does not arrive when expected. A smooth everyday flow is useful, but trust is built when the app explains exceptions clearly. For a finance product, good error communication is part of the feature.
DailyPay Inc has built an app around a genuine pain point, and the current release shows a product that has continued evolving since its 2018 arrival. The strong user rating and broad install base make it worth considering, but they should not replace a personal check of eligibility, timing, and cost. Popularity can tell me that many people find the concept useful; it cannot decide whether an early withdrawal is right for my own budget.
My recommendation is therefore specific rather than universal. If you are eligible, need to bridge a short gap, and can track the reduction in your next paycheck, DailyPay On-Demand Pay can be a sensible emergency cash-flow tool. If you are trying to cover the same shortage repeatedly, prefer predictable long-term budgeting, or cannot tolerate uncertainty around transfer timing, I would choose a savings strategy or another financial option instead.
In the end, I like the app most when it is used deliberately: access only what has already been earned, confirm the terms shown for that transaction, and keep the upcoming payday in view. Used that way, DailyPay On-Demand Pay feels less like borrowing and more like adjusting the calendar of income. That is a useful distinction, but it still requires discipline.
DailyPay On-Demand Pay FAQ
What is DailyPay On-Demand Pay and how does it work?
DailyPay On-Demand Pay is an earned wage access service that may allow eligible employees to access part of their pay before the regular payday. After you work a shift, the available amount is calculated through your employer’s payroll information. You can then transfer available earnings to a linked bank account, debit card, or other supported payment method, while the remaining balance is paid through your normal payroll cycle.
Who can use the DailyPay On-Demand Pay app?
DailyPay is not automatically available to everyone. Access generally depends on whether your employer offers DailyPay as a workplace benefit and whether you meet the employer’s eligibility requirements. After downloading the app, you may need to verify your identity and employment details. If your employer does not participate, or your account information cannot be matched, the service may not be available.
How much money can I access before payday?
The amount available through DailyPay depends on several factors, including your employer’s policies, your reported hours, payroll data, previous transfers, deductions, and account status. You normally cannot withdraw your entire earned paycheck in advance. The app displays your available balance, and that figure can change as new work hours are reported or as payroll information is updated.
Does DailyPay charge fees for transfers?
DailyPay may offer different transfer speeds and payment options, and some options can involve a fee while standard transfers may be free, depending on current terms and your account setup. Fees, limits, and supported destinations can vary by employer, location, and payment method. Before confirming a withdrawal, review the in-app transfer screen carefully to see the exact cost and delivery estimate.
Will using DailyPay affect my regular paycheck or taxes?
Using DailyPay generally gives you early access to wages you have already earned; it does not normally increase your total pay for the pay period. Any amount transferred early is deducted from the paycheck issued on your normal payday, so the final deposit may be smaller. Taxes and other payroll deductions are typically handled through your employer’s regular payroll process, but you should review your pay statement for details.











